


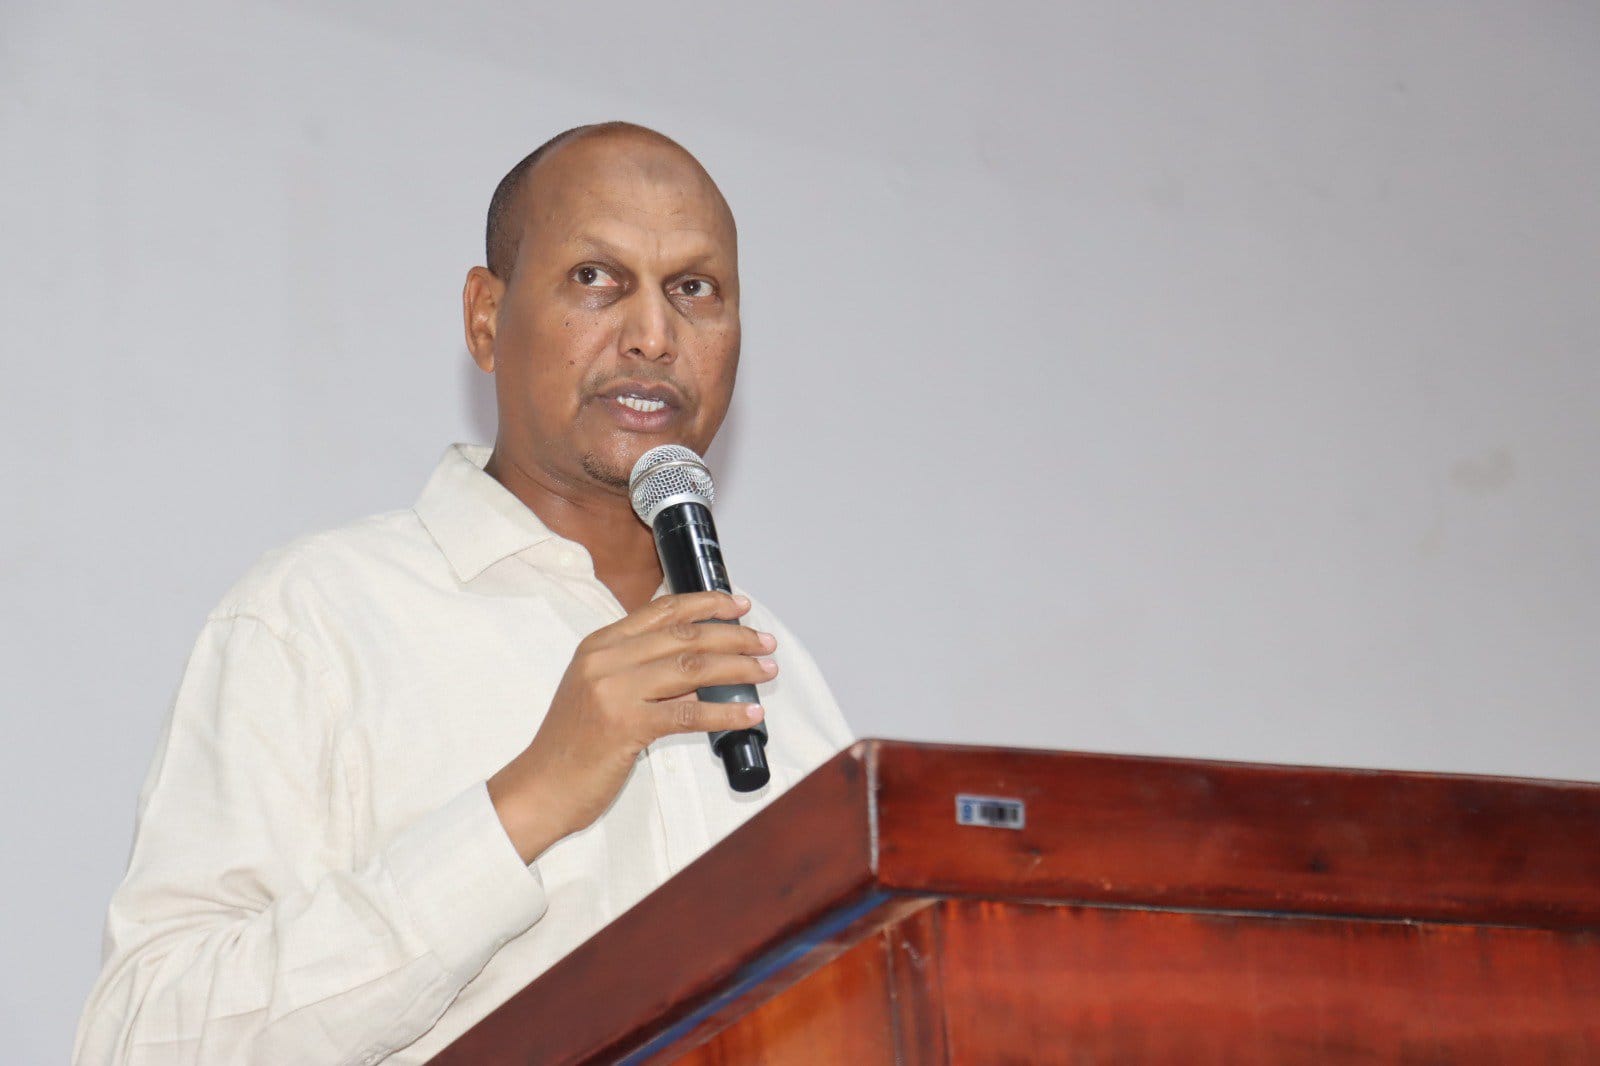
Kenya sits on one of Africa’s most under-exploited economic assets. With a 640-kilometre coastline, territorial waters of about 9,700 square kilometres and an Exclusive Economic Zone spanning roughly 230,000 square kilometres, the country already moves 95 per cent of its international trade by sea. Yet the maritime sector remains, in the words of Principal Secretary Aden Millah, a “sleeping giant.”
Speaking at Bandari Maritime Academy during the FY 2027/28 and Medium-Term Expenditure Framework Stakeholders’ Engagement Forum, Millah issued a clear challenge: Kenyan financial institutions, investors and the private sector must move beyond traditional lending models and actively finance shipping, logistics, shipbuilding, training, inland waterways and the broader blue economy value chain. Government alone cannot unlock it. Capital, innovation and disciplined partnerships must follow.
This is not another aspirational policy speech. It is a hard economic reality check. The numbers are stark. The blue economy currently contributes roughly Sh37 billion to GDP annually through maritime trade and related activities, with government targets aiming to raise that to Sh80 billion by 2026 and Sh150 billion by 2027. Estimates suggest potential to generate several times that figure if properly capitalised. Kenya loses an estimated Sh600 billion every year by remaining a passive transit point rather than an active participant in shipping, ship ownership, marine insurance and value-added services. Ports such as Mombasa handle record cargo volumes—45.45 million tonnes in 2025—yet capacity constraints and limited local participation mean much of the value leaks offshore.
The Opportunity Is Structural, Not Cyclical
Millah correctly framed the maritime sector as a major economic ecosystem rather than a niche government function. The opportunities span international shipping and logistics, shipbuilding and repair, cargo handling, maritime education and training, marine insurance, offshore energy, marine biotechnology, freight forwarding, oil bunkering, maritime tourism, and inland water transport on Lake Victoria, Lake Turkana, Lake Naivasha and Lake Baringo.
Project Mashariki’s efforts to revitalise the Kenya National Shipping Line and expand the KENSHIP Registry point to a deliberate push for greater national shipping capacity. The Vijana Baharia Programme has already trained nearly 10,000 seafarers and placed more than 7,400 in employment, with ambitions to train 35,000 and place over 20,000. Recent partnerships—Maersk’s cadet programme with Kenya Ports Authority, Norwegian ship management commitments for 1,000 Kenyan seafarers by 2030—demonstrate that international demand exists for skilled Kenyan labour.
Inland waterways represent an equally significant frontier. Expanding maritime infrastructure beyond the Indian Ocean coast can lower transport costs for agricultural produce, reduce road congestion, and open new trade corridors within the East African Community. Port PPPs already in the pipeline—approximately US$1 billion for Mombasa berths, container terminals and Lamu assets—signal that private capital is being courted for hard infrastructure. Blue bonds under development, targeting hundreds of millions of dollars for coastal and marine projects, further illustrate the shift toward specialised financing instruments.
The government’s own National Blue Economy Strategy 2025-2030 identifies maritime trade valued at over Sh388 billion annually, while illegal, unregulated and unreported fishing losses are estimated at approximately Sh90 billion. Aquaculture production potential by 2030 stands at 450,000 metric tonnes against current annual production of just 163,605 metric tonnes. These are not marginal gaps. They are investment opportunities hiding in plain sight.
Why Finance Has Stayed Away
The barriers are well known and repeatedly acknowledged. Maritime investments are capital-intensive and long-term. Vessels, shipyards, training simulators, cold-chain facilities and port equipment require patient capital with different risk profiles from conventional real estate or trade finance. Many local banks lack specialised underwriting expertise for marine assets, while pension funds and insurers have historically viewed the sector as opaque or overly regulated. Awareness remains low: a sector that is not widely understood struggles to attract talent, political attention or private capital.
Regulatory and policy work is underway—reviews of the Kenya Maritime Authority Act and Merchant Shipping Act, the Bandari Maritime Academy Bill, and the development of a Maritime Investment Policy and Incentive Regime—but implementation speed and predictability matter more than announcements. Prime Cabinet Secretary Musalia Mudavadi recently acknowledged that “unpredictable or arbitrary regulations could undermine investor confidence,” following concerns raised by the Kenya Shipping Agents Association over provisions of the Maritime Transport Operations Regulations, 2024. Investors need clear, bankable project pipelines, transparent concession processes, and risk-sharing mechanisms that go beyond rhetoric.
The proposed privatisation of Mombasa and Lamu port facilities has also drawn opposition from the Car Importers Association of Kenya, which warns that transferring operational control to private entities, especially international operators, could compromise economic sovereignty and create monopolies. The Kenya Ports Authority has clarified that reforms follow a landlord port model, with government retaining ownership of land and infrastructure while leasing specific operations. Nonetheless, the controversy underscores a broader challenge: private capital must be courted without alienating domestic stakeholders or sacrificing national interest.
What “Full Support” Actually Requires
Millah’s call is not a request for charity. It is an invitation to treat maritime as a core economic priority with measurable returns: jobs, foreign exchange, tax revenue, lower logistics costs, and industrialisation. Financial institutions should develop specialised products—vessel financing, trade finance tailored to shipping cycles, marine insurance capacity, and structured products for training infrastructure and seafarer enterprises. Pension funds and private equity can participate in port PPPs and blue infrastructure. Development finance institutions and commercial banks can co-finance blended structures that de-risk early-stage projects.
There is precedent. Equity Group and MicroSave Consulting recently signed a partnership to deepen financial inclusion in Kenya’s fisheries sector, developing tailored financial products, climate-smart solutions, and insurance mechanisms to de-risk lending along the value chain. The programme targets over 240,000 jobs and has already disbursed significant financing to women and youth. This model—commercial banks partnering with development expertise to design sector-specific instruments—can be replicated across shipping, shipbuilding, and maritime logistics.
The private sector must move from observer to operator. Local participation in shipping lines, ship agency, bunkering, and value-added logistics will retain more revenue onshore. Academia and industry must align curricula with global standards so that Kenyan certificates of competency translate into international jobs rather than remaining under-utilised. Counties, especially coastal and lakeside ones, need to be treated as genuine partners rather than afterthoughts.
Government’s role is to create the enabling environment: predictable regulation, efficient ship registration, competitive incentives, robust maritime security, and domesticated international conventions. Moving “from simply allocating resources to financing results,” as Millah put it, means every public shilling and every private investment must be judged by cargo throughput, employment, cost reductions and revenue generation.
The Cost of Inaction
Kenya cannot industrialise or achieve middle-income status while treating the artery of its trade as an afterthought. Other nations have built national wealth on shipping, shipbuilding and maritime services. The Philippines, which Mudavadi cited as a model, has built a seafarer workforce that supplies the global fleet and generates billions in remittances. Kenya has 19,000 trained seafarers against a medium-term target of 10,000 more and a long-term ambition of 40,000. The global market needs them: an estimated deficit of 89,510 officers and 450,000 ratings by the end of 2026, with an additional 875,000 seafarers required by 2050.
Remaining a pure transit economy means continued leakage of Sh600 billion annually, limited job creation for youth, and vulnerability to external supply-chain shocks. The geography, the trade volumes and the human capital are already in place. Capital and execution are the missing links.
The stakeholders’ forum delivered a straightforward message: Kenya has the location, the resources and the strategic imperative. What it needs now is for banks, investors and the private sector to treat the maritime economy as the high-potential, long-term asset class it is—and to finance it accordingly. The sleeping giant will not wake itself. It requires deliberate, well-structured capital and genuine partnership. The time for half-measures has passed.
Andrew Mwangura is a Mombasa based maritime analyst and former Secretary-General of the Seafarers Union of Kenya.