


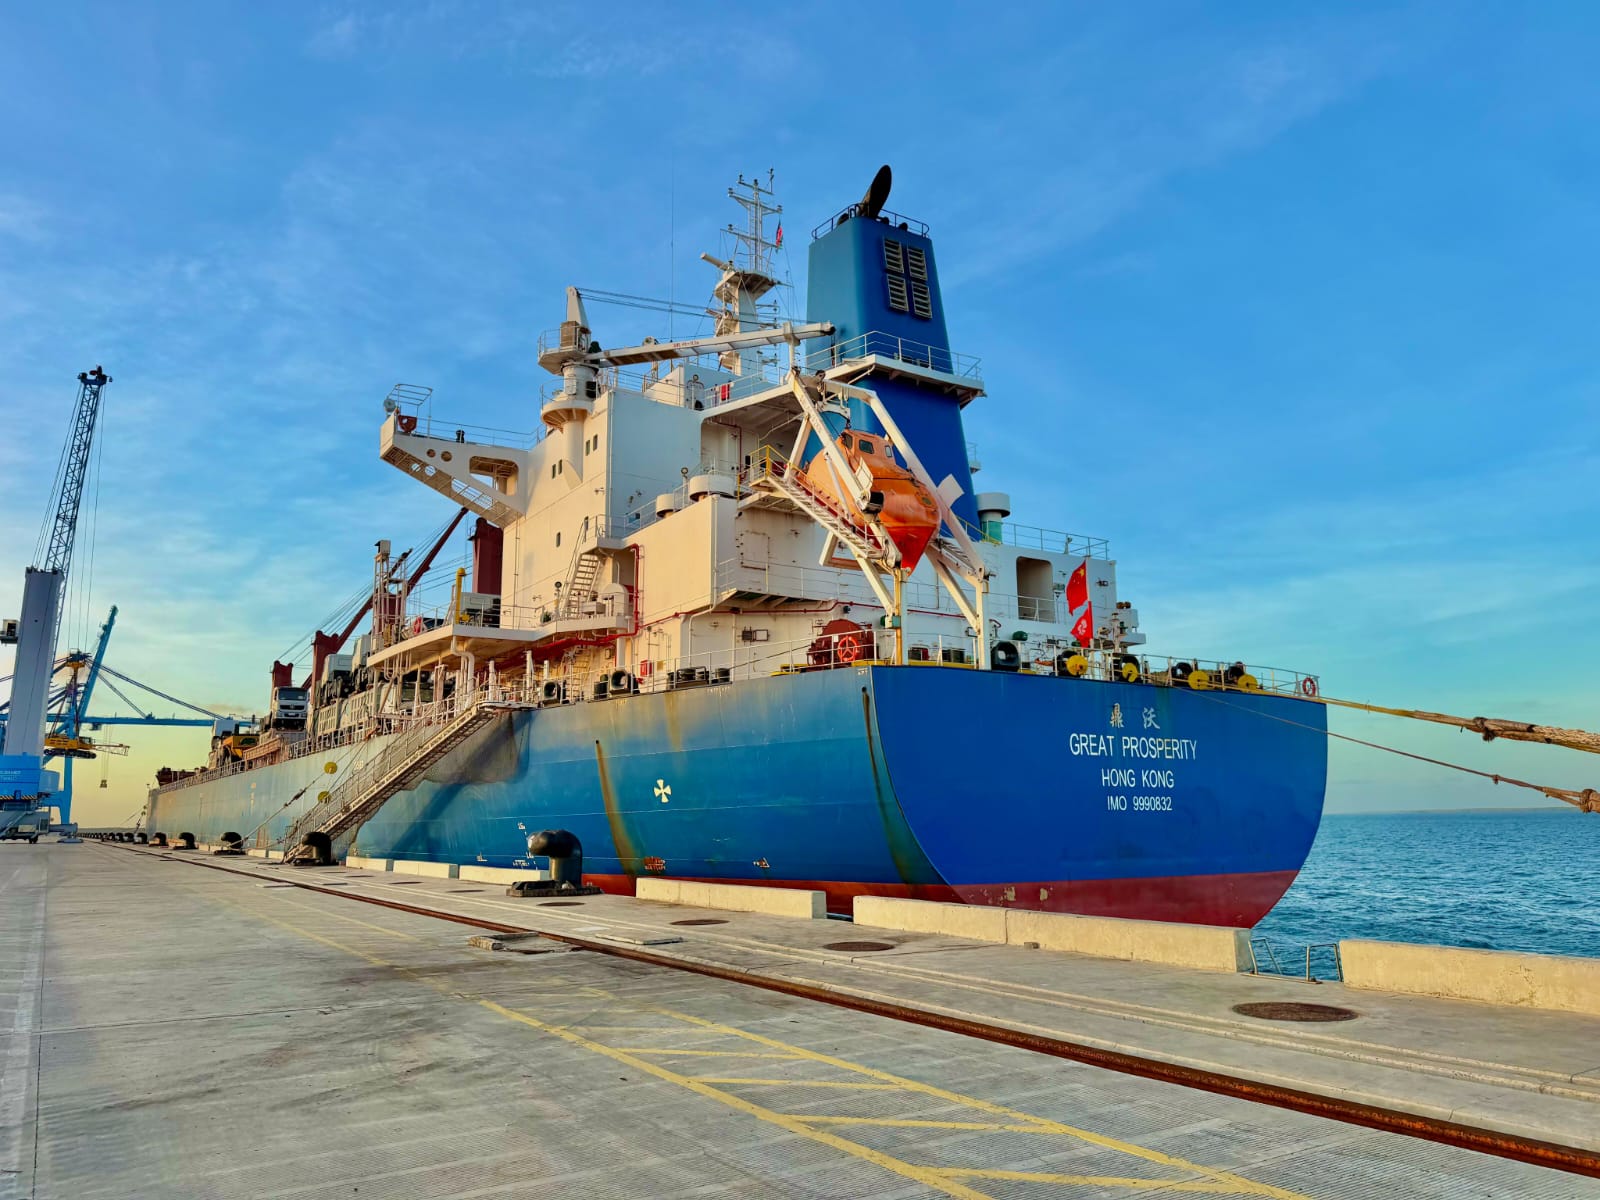
All importers must now secure a digital Marine Cargo Insurance (MCI) certificate from a locally licensed insurer before customs clearance. The process is clear: obtain cover from an Insurance Regulatory Authority (IRA)-licensed underwriter, ensure the certificate is issued and transmitted digitally, and only then proceed with clearance. Non-compliance risks delays, extra costs, and penalties. According to the Kenya Revenue Authority’s (KRA) public notice of 22 October 2026, the enforcement date for blocking non-compliant consignments is 1 November 2026.
This is not a sudden regulatory whim. It is the long-delayed operationalisation of a legal requirement that has existed on Kenya’s statute books since the Finance Act 2017. Section 16A of the Marine Insurance Act (Cap 390) requires any person with an insurable interest in marine cargo to place cover with an insurer licensed under the Insurance Act (Cap 487). Section 20(4) of the Insurance Act makes it an offence to place Kenyan business with an unlicensed insurer without the Commissioner of Insurance’s written approval. For nearly a decade, the rule was largely ignored in practice. Importers routinely relied on foreign policies arranged by overseas suppliers; local underwriters captured only a fraction of a market estimated at between KSh 8 billion and KSh 15 billion annually on imports exceeding KSh 2.5 trillion.
The difference now is technology and political will. A fully integrated digital platform—linking insurers, the IRA, eCitizen/Pesaflow payment systems, industry portals, and KRA’s Integrated Customs Management System (iCMS)—has closed the enforcement gap. A digital certificate is issued against an active Import Declaration Form, premium payment is confirmed electronically, and the certificate is transmitted automatically into iCMS. Without that transmission, a customs declaration cannot proceed. The era of paper certificates, foreign cover notes, and informal workarounds is over.
The Case for the Policy
The economic logic is straightforward. Premiums that previously leaked offshore now remain in Kenya, strengthening the balance sheets of local general insurers, supporting reinsurance capacity, and creating jobs in underwriting, claims, and technology. Digital verification reduces fraud, eliminates the need for manual certificate checking at the port or Inland Container Depots, and should, in theory, accelerate rather than delay clearance once the system matures. It also aligns with the government’s broader digitisation agenda—eCitizen, iCMS, electronic cargo tracking, and the push for paperless trade facilitation.
For the freight and warehousing sector, the Digital Marine Cargo Insurance platform developed in partnership with major underwriters (APA, CIC, Old Mutual, Pacis, Britam and others) represents a proactive industry response. By integrating payment and verification channels, the system seeks to lower transaction friction. Compliance need not mean chaos if the tools are accessible and the process is transparent.
There is also a sovereignty dimension. Countries routinely reserve certain classes of insurance for domestic capacity—motor, workers’ compensation, and in some jurisdictions marine cargo. Kenya is asserting the same principle. In an era of contested global supply chains and rising economic nationalism, retaining insurance risk and premium domestically is a legitimate policy choice.
The Friction Points
Yet the transition is not costless. Many importers, especially smaller ones and those whose supply contracts historically bundled foreign insurance into the CIF price, now face an additional local premium and an extra procedural step. Foreign sellers who previously absorbed the insurance cost may simply pass it on, raising the landed cost of goods. Clearing agents must master new portals and ensure seamless data flow into iCMS; any system glitch or training gap will translate into demurrage, storage charges, and frustrated clients.
There is also the risk of concentration. Early reports suggest a handful of insurers have captured a large share of the new business. While competition should intensify, the initial distribution of capacity and pricing power matters. Small and medium importers may find themselves with fewer options and less negotiating leverage than large multinationals with established local relationships.
Trade facilitation advocates will watch closely. Kenya has invested heavily in positioning Mombasa and the Northern Corridor as efficient gateways for the region. Any perception that the MCI requirement adds friction, even temporarily, could undermine that positioning relative to competing routes. The KRA’s decision to move from the July 2026 “soft” enforcement to hard blocking in November suggests the authorities recognise the need for a transition window—but the window is now closing rapidly.
Balancing Ambition and Practicality
The policy’s success will hinge on three factors. First, system reliability and user support. Training programmes and multi-channel access (insurer portals, industry platforms, eCitizen) are positive signals; they must be sustained and scaled. Second, competitive pricing and product quality. Local insurers must offer cover that is genuinely fit for purpose—adequate limits, reasonable excesses, and efficient claims handling—otherwise the mandate will be felt as pure rent extraction. Third, continuous monitoring of clearance times and complaint volumes. If average dwell times rise materially after 1 November, the authorities should be prepared to fine-tune processes rather than dig in.
Critics who frame the measure purely as protectionism miss the deeper point. Kenya is not banning foreign insurance in principle; it is requiring that the insurance covering risk on Kenyan soil, for cargo destined for the Kenyan market, be underwritten by entities subject to Kenyan regulation, capital requirements, and tax. That is a coherent assertion of regulatory jurisdiction. The digital architecture simply makes the assertion enforceable.
Conclusion
It is now a firm requirement. But “requirement” is only the beginning of the story. The real test is whether the mandatory digital MCI regime becomes a seamless, value-adding component of Kenya’s trade infrastructure or an additional tax on commerce that slows the very growth it seeks to capture. Local insurers have been handed a substantial new market. Importers and agents have been handed a new compliance obligation. The government has been handed the responsibility to ensure the system works.
If all three parties treat the November deadline as the start of continuous improvement rather than the end of the conversation, Kenya can demonstrate that economic sovereignty and efficient trade facilitation are not mutually exclusive. The cargo will keep moving. The question is whether the insurance that protects it will also strengthen the economy that depends on it.