


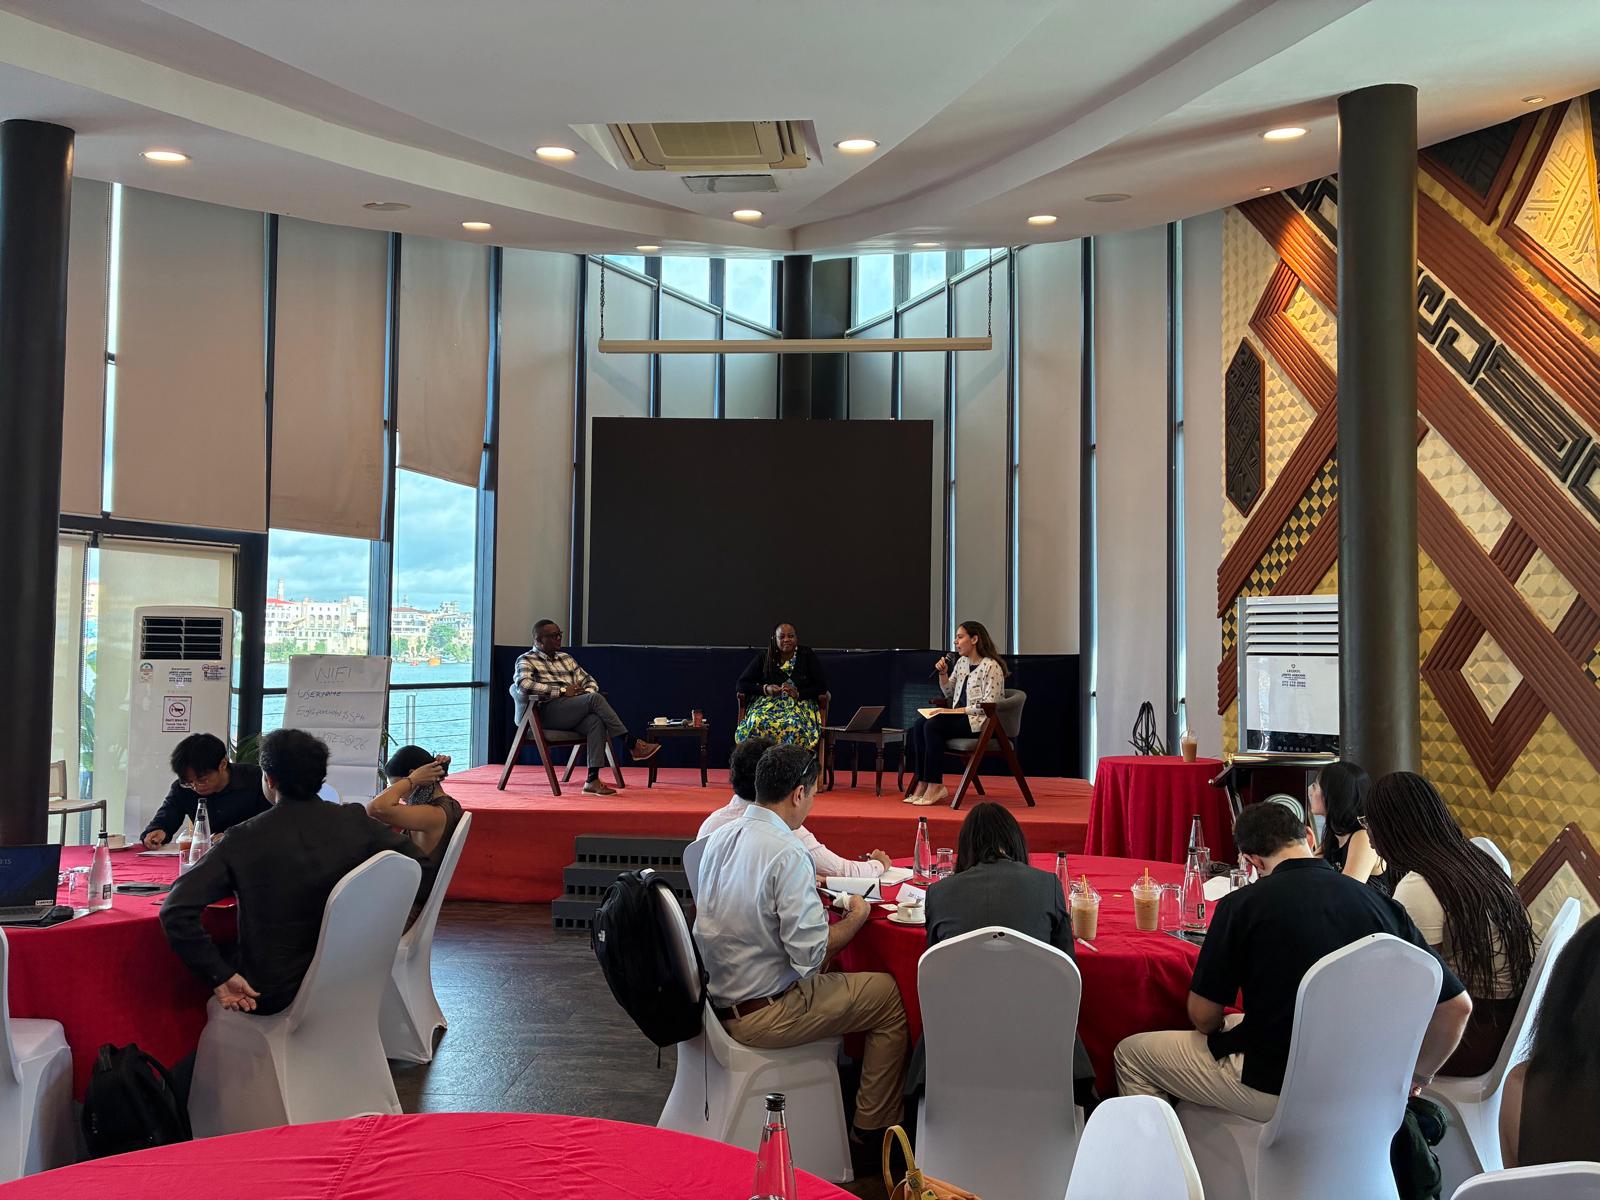
The recent high-level maritime roundtable at English Point Marina laid bare the commercial realities facing the Port of Mombasa. The discussions revealed that the port is far more than a gateway; it is the epicenter of a complex contest pitting global shipping conglomerates, regional governments, and local businesses against one another—all competing to shape the future of the Northern Corridor. Yet the most uncomfortable truth to emerge was this: though Kenya owns and operates one of Africa’s most strategic ports, it exercises only limited influence over the commercial forces that determine how that gateway actually functions.
The Congestion Paradox
The observations from maritime practitioner Elijah Mbaru should sound an alarm for every policymaker. Handling over 45 million metric tonns of cargo annually is an impressive achievement, yet chronic congestion, lengthy cargo dwell times, empty-container shortages, and escalating surcharges persistently erode the port’s competitive edge.
The bottleneck is no longer purely infrastructural. Kenya has invested heavily in deeper berths, expanded terminals, and enhanced road and rail links. Today’s constraints lie increasingly at the commercial and regulatory interface—between global shipping lines, port operators, customs authorities, and inland logistics providers. Every additional day a container sits at the port translates directly into higher costs: ships face delays, importers incur storage penalties, exporters lose margins, and consumers ultimately absorb the price hikes. Institutions like the Kenya Ports Authority (KPA) and Kenya Maritime Authority (KMA) have modernized operations admirably. However, regulation must evolve at the same breakneck pace as global shipping’s business models. Commercial efficiency cannot thrive when administrative processes lag behind technological innovation.
The New Geopolitics of Trade Corridors
Dr. Beatrice Matiri correctly placed Mombasa within the wider geopolitical contest reshaping global supply chains. Ports today are no longer mere transport facilities; they are instruments of economic diplomacy. Chinese-backed infrastructure, Gulf-owned shipping interests, and European maritime conglomerates are collectively redrawing the competitive landscape of African logistics.
Meanwhile, Tanzania’s massive investment in its Central Corridor and standard-gauge railway represents a direct challenge to Mombasa’s historical dominance. Equally significant is the growing attention directed toward the Port of Lamu. Whether Lamu emerges as a genuine commercial competitor or remains an aspirational vanity project will depend not on the size of its berths, but on its ability to build a complete logistics ecosystem—integrated services, efficient customs, competitive tariffs, and reliable hinterland connectivity. Infrastructure alone does not attract cargo; efficient commercial ecosystems do.
The Untapped Promise of the African Continental Free Trade Area
Perhaps the greatest irony highlighted during the discussions concerns Africa’s own trading relationships. Despite the implementation of the African Continental Free Trade Area (AfCFTA), intra-African trade remains stubbornly low at roughly 17% of total continental commerce. It remains easier, faster, and often cheaper to move a container from Shanghai to Mombasa than from Mombasa to Kigali. This paradox reflects persistent non-tariff barriers, fragmented customs procedures, duplicated border inspections, and inconsistent regulatory frameworks that continually impede regional commerce. Until East African governments treat logistics efficiency with the same urgency as infrastructure development, the Northern Corridor will continue to underperform its enormous potential.
When Global Risk Becomes Local Pain
One of the roundtable’s most revealing moments was its dissection of how commercial risk is distributed throughout the supply chain. Whenever geopolitical crises disrupt international shipping—whether in the Strait of Hormuz, the Red Sea, or elsewhere—insurance premiums spike, and carriers impose emergency surcharges. Rarely do these multinational giants absorb the additional costs. Instead, the burden cascades down the chain until it falls on those least able to bear it: truck operators, clearing agents, small importers, and ordinary consumers.
Kenya remains largely a price-taker within global shipping markets. Those who own the vessels and control the routes possess the leverage. Without stronger regional cooperation, greater collective bargaining power, and competitive indigenous shipping capacity, East African businesses will continue absorbing external shocks over which they have little control.
Reinventing the Kenyan Ship Agent
The discussions also highlighted an existential challenge for Kenyan ship agents. Digitalization, industry consolidation, and direct carrier-to-shipper contracts are steadily reducing the traditional intermediary role of local agents. Survival will demand reinvention. Tomorrow’s successful agent must offer far more than vessel representation; they must become trusted advisers in customs compliance, regional logistics, digital trade facilitation, and maritime risk management. Preserving this indigenous commercial expertise is strategically vital. Without knowledgeable local intermediaries, Kenya risks surrendering even greater commercial sovereignty to foreign corporate headquarters.
From Transit Port to Value-Creating Maritime Hub
The central takeaway from the English Point Marina dialogue is that Kenya must redefine what success looks like. A port’s true value is not measured solely by cargo volumes or vessel calls, but by the economic activity, industrial investment, employment, and logistics innovation it generates. Kenya should pursue policies that transform Mombasa from a transit gateway into a fully integrated maritime business hub. This requires deeper regional integration, greater transparency in shipping tariffs, accelerated digital facilitation, harmonized customs procedures, and a credible regional maritime arbitration mechanism to resolve commercial disputes fairly. The future belongs not to ports that merely move cargo, but to ports that create value.
Conclusion
The English Point Marina roundtable was more than an industry discussion; it was a timely diagnosis of the structural challenges confronting East Africa’s most important maritime gateway. Mombasa remains the economic heartbeat of the region, but sustaining that position will require more than expanding infrastructure. Kenya must strengthen its commercial leverage, modernize its regulatory architecture, and build institutions capable of protecting national interests within an increasingly competitive global shipping industry.
Global powers will continue investing in African ports, supply chains will keep evolving, and geopolitical shocks will remain inevitable. The critical question is whether Kenya will continue to serve merely as a convenient port of call, or whether it will finally emerge as the commercial anchor that shapes the future of maritime trade in Eastern and Central Africa.
Andrew Mwangura is a Mombasa-based Public Intellectual and Maritime Affairs Analyst.