


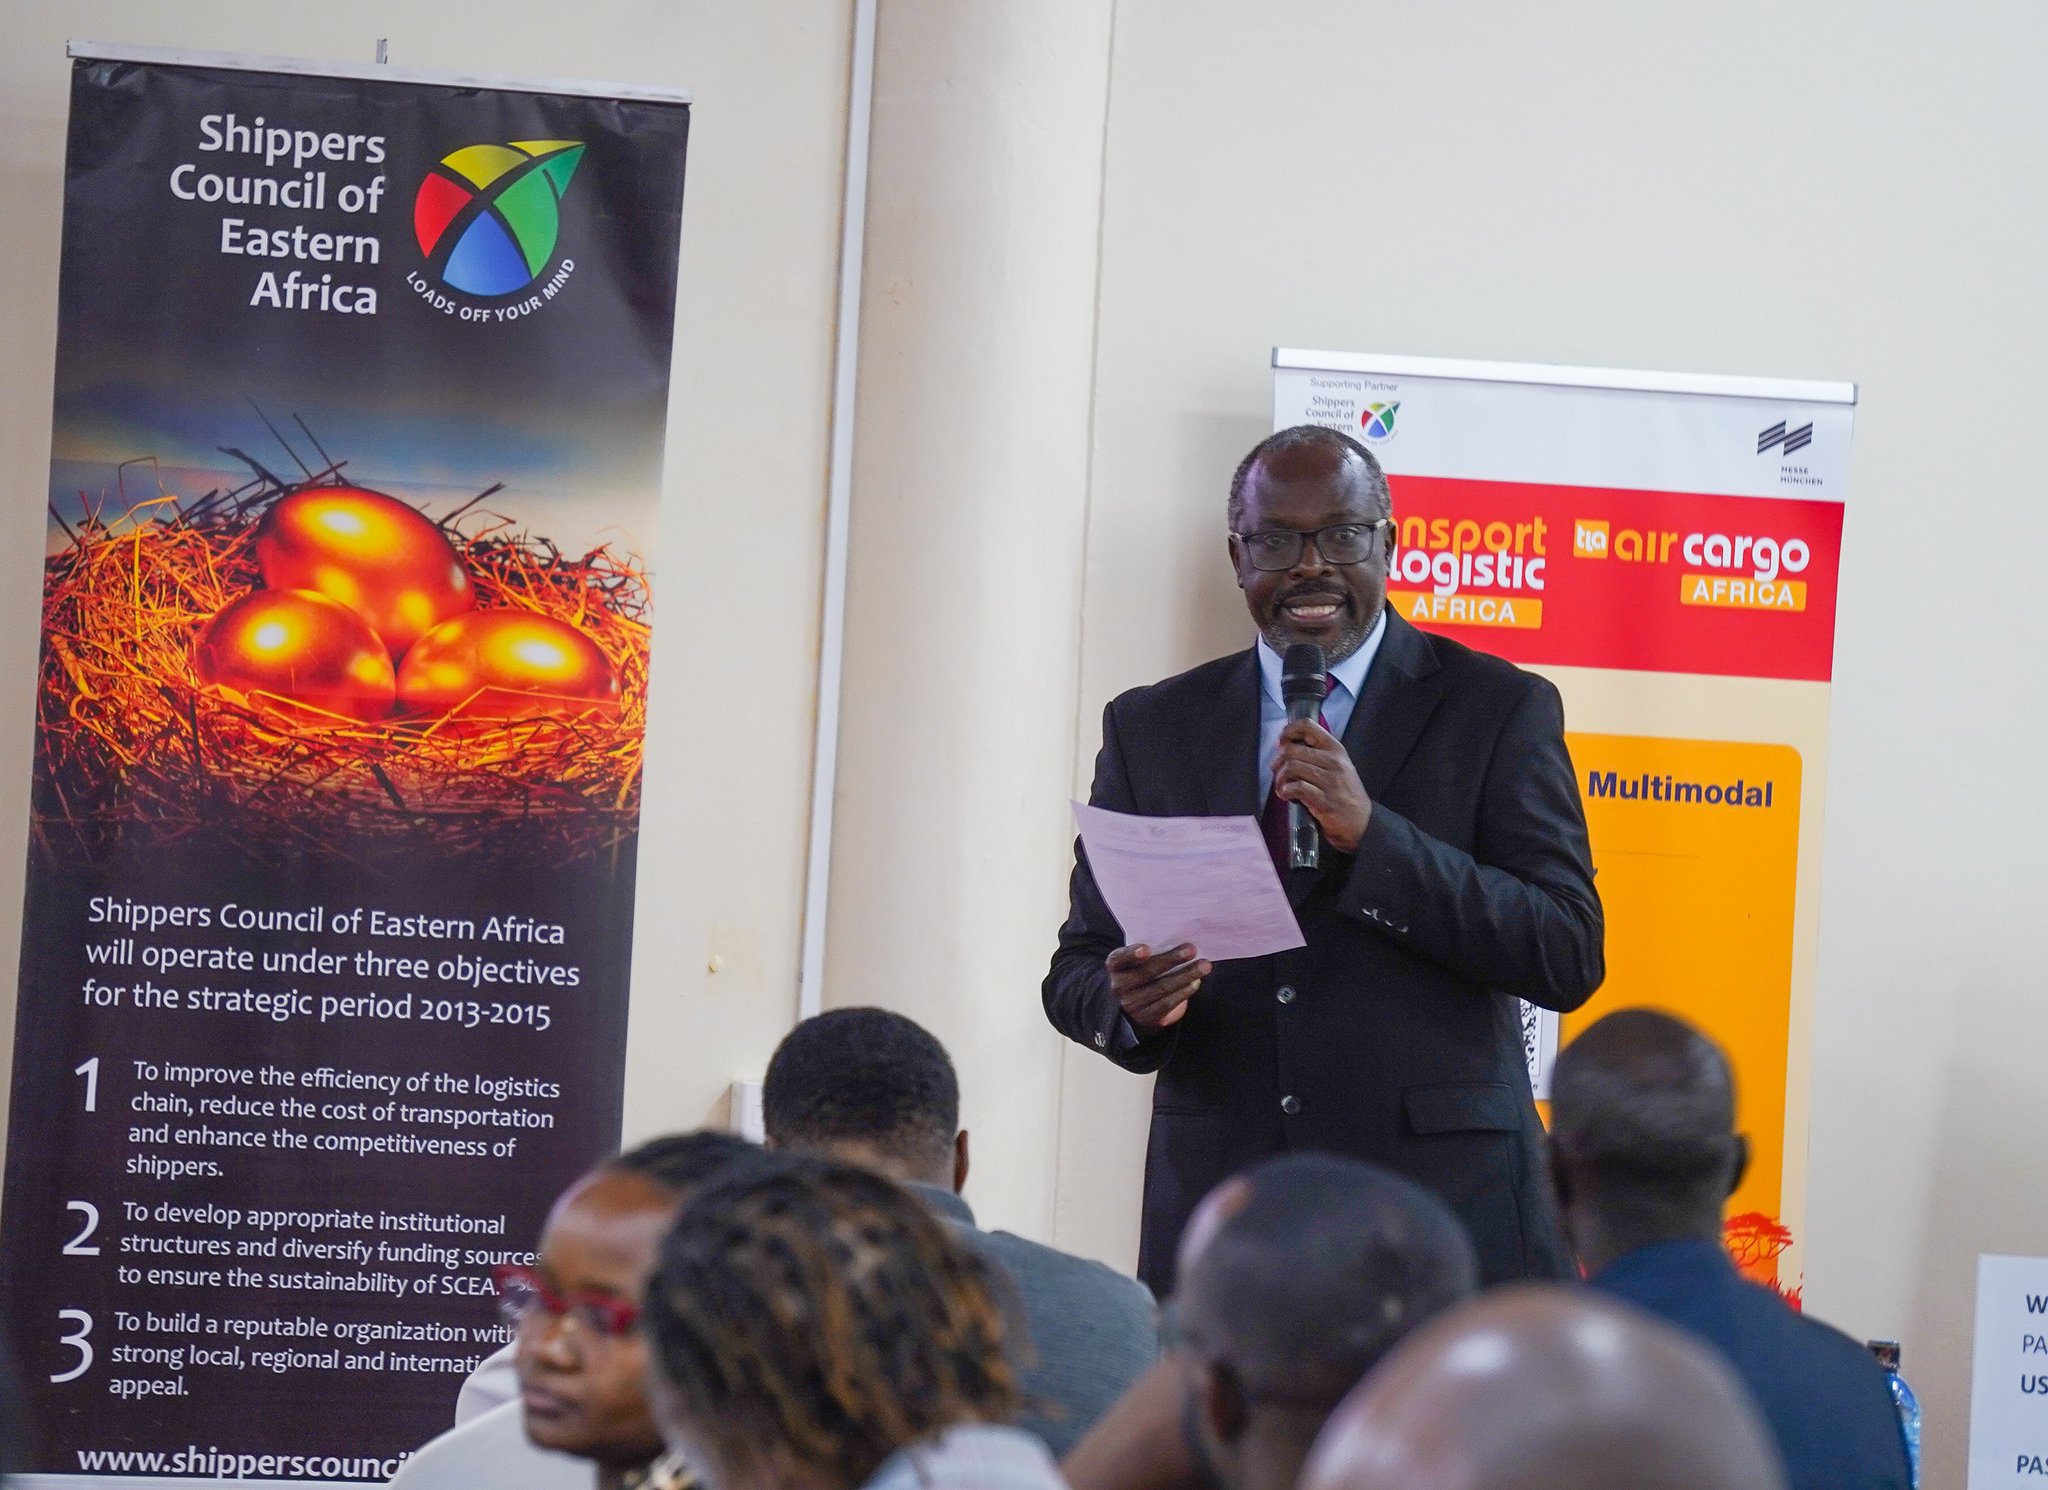
In a packed hall at the Panari Hotel in Nairobi, more than 170 members of the Shippers Council of Eastern Africa (SCEA) and industry stakeholders recently convened for a high-stakes sensitization engagement. Government agencies and technical experts walked participants through the latest regulatory requirements shaping cargo importation, exportation, shipping, freight forwarding, customs clearance, and logistics. The agenda was dense and consequential: Kenya Revenue Authority’s Advance Cargo Declaration (ACD) and export declaration rules, KenTrade/NEMA Phase II implementation, Kenya Nuclear Regulatory Authority (KNRA) cargo monitoring, screening and testing requirements, and Intertek’s inspection, testing, certification and Pre-Export Verification of Conformity (PVoC) services.
Members signaled willingness to comply. They also delivered a clear message: simplify and expedite approval processes, and stop the steady accumulation of fees and charges that raise the cost of doing business and erode trade competitiveness. That tension—legitimate regulatory goals versus operational friction and cost—defines Kenya’s current logistics moment. It deserves serious analysis rather than routine celebration of “stakeholder engagement.”
The Regulatory Wave and Its Rationale
Kenya is tightening pre-arrival visibility and multi-agency oversight for good reason. The ACD platform, launched for containerized cargo destined for Kenyan ports, requires exporters to obtain a reference code at the port of loading by uploading a draft bill of lading, commercial invoice, freight invoice, and export declaration. The code must then be endorsed on the bill of lading. The system aims to give Customs advance data for risk assessment, faster legitimate clearance, and stronger controls against smuggling, undervaluation, and non-compliant goods.
Parallel tracks add layers. KenTrade’s National Electronic Single Window continues to evolve, with NEMA Phase II bringing environmental compliance deeper into the digital flow. KNRA requirements introduce monitoring, screening, and testing for cargo with potential nuclear or radiological relevance—sensible in a security and safety context, but new operational terrain for many shippers. Intertek’s PVoC and related services remain central to quality and standards enforcement for many product categories.
These measures sit within a broader digital and security modernization push. Advance information systems are common globally. They can reduce physical inspections, improve targeting, and support revenue integrity. SCEA’s own advocacy history shows the value of constructive engagement: earlier efforts helped shorten dwell times, expand free periods, and push non-intrusive verification. Dialogue remains essential.
Where Friction Becomes Cost
Willingness to comply does not erase practical problems. Stakeholders repeatedly note that the ACD creates another declaration layer even though similar data already flows through Import Declaration Forms, shipping manifests, the KenTrade single window, and existing KRA systems. Draft bills of lading are often unavailable at the precise moment the platform demands them. Timing mismatches, portal learning curves, and the need to coordinate across origin-country agents introduce delay risk. Non-compliance can mean rolled cargo, fines, or holds—costs that ultimately land on the importer or exporter.
Fees and charges compound the issue. Each new process, certificate, screening, or verification step carries direct and indirect costs: service fees, agent time, demurrage risk, working capital tied up in longer cycles, and the administrative burden of navigating multiple systems. For high-volume operators these can be absorbed; for SMEs and consolidated cargo traders they are disproportionately heavy. Kenya’s logistics cost base is already a competitiveness constraint. Layering incremental charges without clear, measured offsets in clearance speed or reduced physical interventions risks making the Northern Corridor and Mombasa less attractive relative to regional peers.
Inter-agency coordination remains incomplete. More than thirty agencies touch trade processes. Digital platforms reduce some friction, yet parallel requirements, differing data standards, and sequential approvals still create bottlenecks. The promise of a true single window is diluted when new specialized regimes operate as add-ons rather than fully integrated modules.
Trade Competitiveness at Stake
Eastern Africa’s shippers compete on reliability and total landed cost. Delays and unpredictability raise insurance, inventory, and financing costs. Rising compliance overheads make Kenyan-origin or Kenya-routed goods less competitive under AfCFTA and in global value chains. Transit cargo—significant for the region—feels these pressures too; anything that slows the corridor or raises its effective cost weakens Kenya’s hub status.
SCEA’s call for simplification and expediting is therefore not resistance to regulation. It is a demand for design that achieves security, revenue, and standards goals with the least possible distortion to legitimate commerce. Best practice elsewhere emphasizes risk-based approaches, mutual recognition of data already submitted, clear lead times, capacity-building support for SMEs, and transparent impact assessments before new fees or mandatory steps are introduced.
A Path Forward
Constructive engagement must move beyond information sessions to measurable outcomes. First, map every data element required by ACD, NEMA Phase II, KNRA, and PVoC against existing submissions and eliminate pure duplication. Second, publish clear service-level standards for reference-code issuance and inter-agency handoffs, with public dashboards on average processing times. Third, subject proposed new charges to a formal competitiveness test: quantify the expected gain in compliance or security and the expected increase in logistics cost, then adjust design or sequencing accordingly. Fourth, expand targeted sensitization and technical assistance for smaller operators so compliance capacity rises with regulatory ambition.
Government agencies and SCEA share an interest in a logistics sector that is both secure and competitive. The Panari engagement demonstrated that the private sector will show up and engage in good faith. The test now is whether the next round of implementation reduces friction rather than merely documenting it. Kenya’s trade ambitions—deeper regional integration, higher-value exports, and reliable corridor performance—depend on getting that balance right. Compliance without competitiveness is a short-term victory that risks longer-term erosion of the very trade volumes the rules seek to govern.