


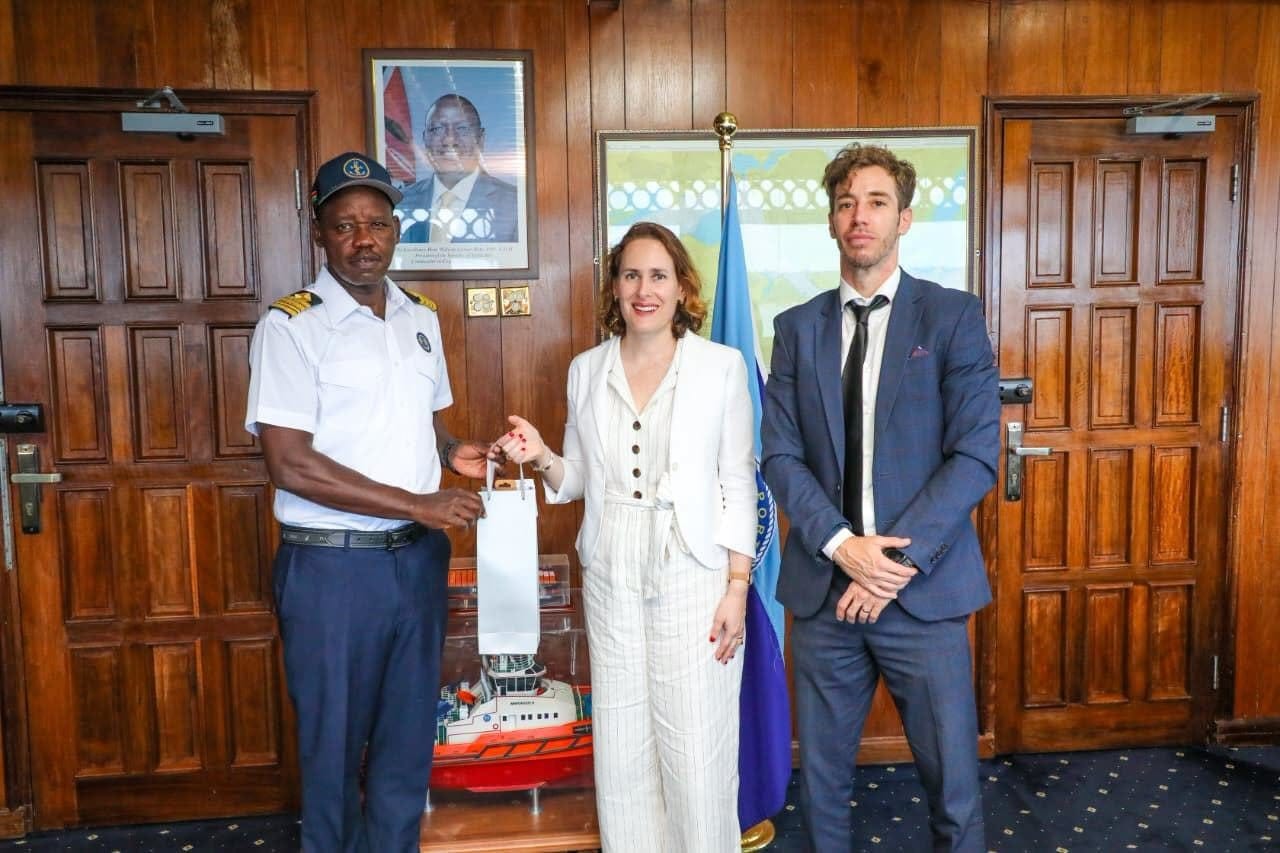
Argentina’s decision to court Kenya’s Port of Mombasa is more than a routine diplomatic courtesy call. It is a calculated bid to convert geography into strategy. By positioning East Africa’s busiest gateway as the logistical hinge for Argentine goods flowing into the wider East and Central African hinterland, Buenos Aires is signalling that it intends to treat the Indian Ocean corridor not as a distant curiosity but as a serious commercial frontier.
On 7 October 2026, Chargé d’Affaires Cynthia Mulville and Head of Trade and Economic Affairs Demian Dobry sat down with Kenya Ports Authority Chief Executive Officer Captain William Ruto. The Argentine side is conducting a regional marketing assessment; the Kenyan side is offering investment openings in port expansion and Special Economic Zones. The conversation was framed around port efficiency, logistics, infrastructure, and supply-chain connectivity. Beneath the polite language lies a clearer proposition: Argentina wants reliable, scalable access to markets that collectively represent tens of millions of consumers, and Mombasa is the most efficient door currently available.
Why Mombasa Matters Now
The Port of Mombasa is no longer merely Kenya’s main harbour. It is the maritime backbone of the Northern Corridor, moving cargo for Uganda, Rwanda, South Sudan, eastern Democratic Republic of Congo, and beyond. In 2025, it handled a record 45.45 million tonnes of cargo, up 10.9 percent year-on-year, with container throughput climbing above 2.1 million TEUs and transit volumes rising nearly 20 percent. Capacity is still expanding: Berth 19B, planned additional berths, terminal operating system upgrades, and the Dongo Kundu Special Economic Zone are designed to absorb precisely the kind of new trade flows Argentina is contemplating.
For a distant exporter, this infrastructure is decisive. Shipping Argentine cereals, soy products, vegetable oils, or other bulk and containerised goods directly into Mombasa, then moving them inland by rail or road, is far more practical than trying to service each landlocked market through fragmented, higher-cost routes. The port’s growing digital systems and hinterland connectivity reduce the friction that has historically kept Latin American suppliers at the margins of East African trade.
The Trade Relationship That Already Exists—and What It Could Become
Bilateral volumes are already material on one side. Argentine exports to Kenya reached roughly $200–237 million in recent data, dominated by cereals. Kenya is a notable buyer of Argentine wheat; Argentina ranks as a significant supplier in that market. The reverse flow remains tiny—Kenyan exports to Argentina hover in the low millions—creating a classic imbalance that both sides have incentive to correct.
Argentina’s broader export profile offers clear adjacency. Beyond grains, the country is a competitive producer of soymeal and oil, wine, agricultural machinery and technology packages, and veterinary products. Kenyan and regional demand for food security solutions, higher-productivity farming inputs, and cold-chain logistics is rising. Argentina’s experience with large-scale, technology-intensive agriculture is precisely the kind of capability East African governments say they need. Earlier diplomatic engagement has already flagged agricultural technology, food security, and related technical cooperation as priorities.
The Port of Mombasa conversation therefore sits inside a larger South-South logic. Argentina is not seeking charity or preferential aid. It is seeking commercial scale. Kenya, for its part, is actively marketing its ports and SEZs to multiple partners—Germany, Egypt, the Netherlands, Japan, and others—precisely because it understands that diversified traffic strengthens the corridor’s resilience and revenue base.
Special Economic Zones and the Investment Angle
Captain Ruto’s emphasis on investment opportunities linked to port expansion and SEZs is not rhetorical. The Dongo Kundu zone, covering thousands of acres with dedicated berth development, is being positioned as an integrated industrial and logistics platform. Early investors are already on site; dozens more have expressed interest. A separate Mombasa SEZ project involving private partners is advancing with targets for manufacturing, processing, and export-oriented activity.
For Argentine firms, these zones could serve multiple purposes: processing or blending bulk commodities closer to final markets, establishing regional distribution hubs, or co-locating agricultural technology and service operations. The combination of port access, industrial land, and preferential treatment inside an SEZ lowers the cost of serving not only Kenya but the entire Northern Corridor. That is the real prize Argentina appears to be assessing.
Challenges That Cannot Be Wished Away
Distance remains the most obvious constraint. The sailing time from the River Plate to Mombasa is long; freight rates and schedule reliability will determine whether Argentine cargo can compete with nearer Asian or Middle Eastern suppliers. Non-tariff barriers, phytosanitary requirements, and the still-limited presence of Argentine commercial networks on the ground add further friction. Kenya’s own industrialisation ambitions mean it will prefer value-added processing and technology transfer over pure commodity dumping.
Political and economic volatility on both sides of the Atlantic also matters. Argentina’s macroeconomic cycles have historically disrupted consistent export strategies. Kenya’s regulatory environment and infrastructure delivery timelines have improved, but large projects still face the usual execution risks. Neither side should romanticise the relationship. Realistic commercial mapping—specific product lines, volume targets, logistics partnerships, and risk-sharing arrangements—will matter more than summit communiqués.
A Template for Smarter South-South Engagement
If the engagement moves beyond assessment into concrete shipping services, investment commitments, or technical cooperation agreements, it could become a useful model. Latin America and Africa have long spoken of South-South solidarity while remaining relatively disconnected in practical trade terms. Using an established, expanding port hub as the connective tissue is a pragmatic way to close that gap.
Kenya gains diversified cargo, potential investment in its logistics and industrial platforms, and another partner interested in the long-term health of the Northern Corridor. Argentina gains a foothold in a fast-growing regional market and a logistical platform that multiplies the value of every tonne it can place into Mombasa. Both countries are members of larger economic communities—Mercosur on one side, the East African Community and AfCFTA on the other—whose rules and aspirations ultimately favour denser intra-global-South commerce.
The meeting between Mulville, Dobry, and Captain Ruto is therefore best read as the opening move in a longer campaign. Whether it yields lasting commercial results will depend on whether Argentine exporters and Kenyan logistics planners can translate diplomatic interest into reliable schedules, competitive costs, and tangible projects inside the port and its adjacent economic zones. Geography has already done half the work by placing Mombasa at the centre of East and Central African trade. The rest is now a question of execution.